Economy
Asian Markets Await US Inflation Data Amid China Economic Concerns


Asian markets faced challenges on Tuesday (12 September) in their attempt to follow the positive trends in Wall Street and Europe. Investors are anxiously awaiting the release of US inflation data, while lingering concerns about China’s economy continue to weigh on sentiment.
The upcoming consumer price index (CPI) report holds significant importance as it influences the Federal Reserve’s policy decisions. The next Fed meeting is expected to result in interest rates being maintained, but market participants will closely analyze the accompanying statement for insights into the central bank’s future plans.
Equities have encountered difficulties this month due to fears that strong economic indicators and a robust job market may prompt the Fed to implement further tightening measures this year to combat inflation. The situation is further complicated by mixed signals from Fed officials, with some advocating for rate hikes and others favoring a wait-and-see approach to gauge the impact of over a year of rate adjustments.
Fed Chairman Jerome Powell has emphasized that decisions will be data-driven, causing investors to interpret weak economic data as positive news for the future interest rate outlook.
Chris Larkin, Managing Director of Trading and Investing at E*Trade from Morgan Stanley, noted, “This week is more likely to be a ‘good news is good, bad news is bad’ story. The market’s ability to rebound in the near term could hinge on this week’s inflation numbers, especially Wednesday’s CPI.”
Leading economists from major global banks have expressed the view that the Fed is unlikely to implement further rate hikes and may begin reducing borrowing costs in the new year. They also predicted that the United States will avoid a recession. Simona Mocuta, Chair of the 14-member American Bankers Association’s Economic Advisory Committee, stated, “Given both demonstrated and anticipated progress on inflation, the majority of the committee members believe the Fed’s tightening cycle has run its course.”
Meanwhile, tech firms led a surge in all three major indexes on Wall Street, while Asian markets displayed mixed performance. Tokyo, Taipei, and Manila saw slight gains, but Hong Kong, Shanghai, Seoul, Sydney, Singapore, Wellington, and Jakarta all experienced declines.
Concerns about China’s economy continue to dampen investor sentiment, despite some signs of improvement such as a return to inflation and a smaller-than-expected decline in exports and imports. There are calls for the Chinese government to unveil a substantial stimulus package akin to the one implemented during the 2008 global financial crisis to boost growth and support the property sector.
In the currency markets, the Japanese yen slightly weakened against the US dollar after receiving a boost from comments by the Bank of Japan’s head, hinting at a potential shift away from the current ultra-loose monetary policy.

The International Monetary Fund (IMF) has urged Bangladesh to maintain a tight monetary policy to contain inflation, while stressing that monetary tightening alone will not be enough to restore economic stability.
Inflation in Bangladesh rose to 8 per cent in September, according to the IMF. The Washington-based lender has called for broader reforms in the financial sector, stronger revenue mobilisation and improvements in overall economic management to address the country’s persistent economic challenges.
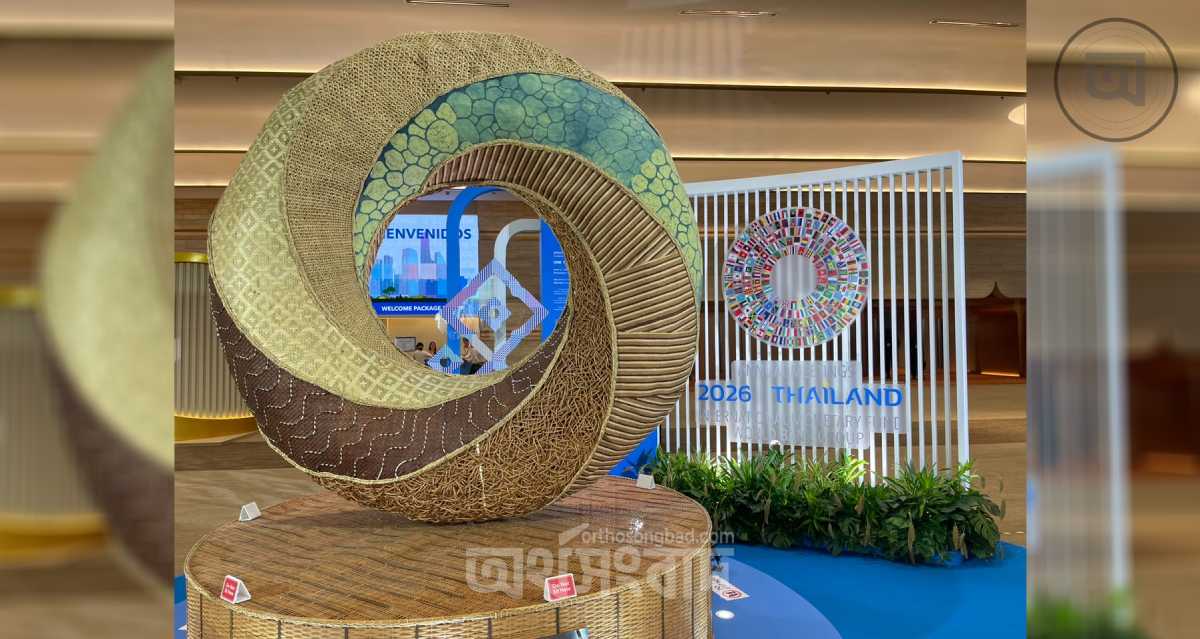
Sonali Jain-Chandra, deputy director of the IMF’s Asia and Pacific Department, made the remarks in response to a question at a news conference on the economic outlook for Asia and the Pacific, held on the sidelines of the IMF and World Bank Group annual meetings in Bangkok, Thailand.
Asked whether tight monetary policy alone would be sufficient to tackle inflationary pressures that have persisted for more than three and a half years, Jain-Chandra said maintaining a restrictive monetary stance was important, but needed to be accompanied by other reforms.
Bangladesh is currently facing challenges in three key areas: revenue mobilisation, the financial sector and inflation, she said.
The IMF also expressed concern over the fragile state of Bangladesh’s financial sector, saying a credible reform strategy was needed to strengthen the sector’s capacity and ensure stability.
The fund also highlighted the country’s persistently weak revenue collection. Bangladesh’s tax-to-GDP ratio has declined over time and currently stands at around 7 per cent, placing it among the lowest in the world, according to the IMF.
The IMF stressed the need for a coordinated effort to increase revenue collection, saying higher government revenues were essential to finance development expenditure and strengthen the financial sector.
It called for necessary reforms to the revenue system and effective measures to improve the government’s capacity to generate income.
Talks Under Way on New IMF Programme
Meanwhile, discussions are continuing on a potential new lending programme for Bangladesh.
Jain-Chandra said Bangladeshi authorities approached the IMF in May for support under a new programme after deciding not to draw further instalments under the previous arrangement.
In response to the request, an IMF mission visited Dhaka in July to discuss various aspects of Bangladesh’s economic reform agenda.
According to Jain-Chandra, the reform issues discussed during the visit were closely aligned with the recommendations outlined in the IMF’s Article IV consultation for Bangladesh earlier this year.
The IMF has remained in regular contact with Bangladeshi authorities since the July visit, she said.
Jain-Chandra added that the fund remained closely engaged with the authorities and was ready to support Bangladesh in initiating the reforms needed to address its economic challenges.
The International Monetary Fund (IMF) has projected that Bangladesh’s gross domestic product (GDP) will grow by 3.2 per cent in the 2026-27 fiscal year, while average inflation could rise to 10.9 per cent, signalling mounting pressure on the country’s economy.
The projections were outlined in the IMF’s World Economic Outlook (WEO) report, released on Tuesday.
The latest growth forecast marks a significant downward revision from the 4.3 per cent projected by the IMF in April. The fund had subsequently forecast growth of 3.5 per cent in July before lowering its estimate further to 3.2 per cent.
The IMF has also sharply revised its inflation outlook for Bangladesh. In April, it projected average inflation of 6 per cent for the 2026-27 fiscal year. The latest estimate raises that figure to 10.9 per cent.
The combination of slower economic growth and persistently high inflation points to continued pressure on Bangladesh’s macroeconomic stability.
Bangladesh growth outlook trails other forecasts
The IMF’s latest growth projection for Bangladesh is lower than those of other major international development institutions.
The World Bank has forecast GDP growth of 3.4 per cent for Bangladesh in the 2026-27 fiscal year, while the Asian Development Bank (ADB) has projected growth of 4 per cent.
According to the IMF, Bangladesh’s economy grew by 3.6 per cent in the 2025-26 fiscal year, following growth of 3.5 per cent in the preceding fiscal year.
India, Bhutan expected to grow faster
The IMF has projected stronger economic growth in neighbouring countries, with India’s economy expected to expand by 7 per cent and Bhutan’s by 6.9 per cent in the relevant fiscal year.
The contrasting forecasts highlight the challenges facing Bangladesh as it seeks to restore economic momentum while tackling persistent inflation.
The IMF’s latest projections come as the annual meetings of the IMF and the World Bank Group are underway in Bangkok, Thailand.
Bangladesh’s economic situation, reform programmes and efforts to secure financing from development partners are among the key issues receiving attention during the meetings.
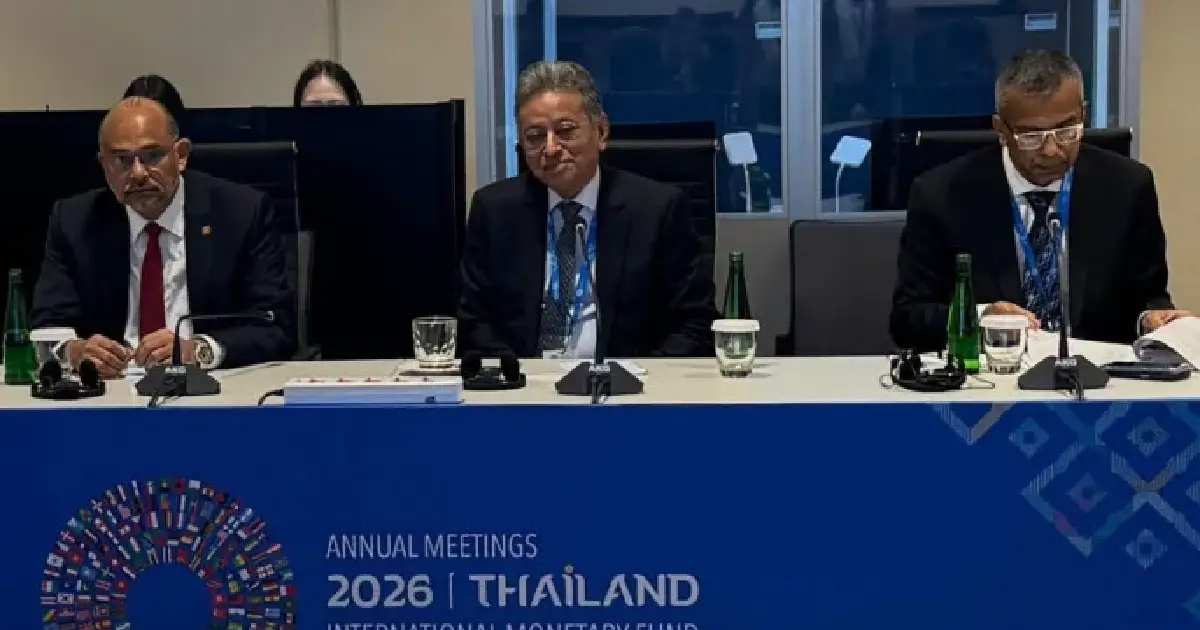
The World Bank supports the Bangladesh government’s policies to address the country’s current economic challenges, restore stability and implement medium- and long-term development plans, Finance Minister Amir Khasru Mahmud Chowdhury said on Tuesday.
He said the global lender was broadly aligned with Bangladesh’s economic programmes and policy priorities and would continue to support the country’s economic recovery and future development.
The finance minister made the remarks while speaking to journalists after a meeting with a World Bank managing director in Bangkok, Thailand, on October 13.
Amir Khasru said Bangladesh’s economy was facing significant challenges when the current government took office. Alongside dealing with the financial and economic burdens inherited from the previous period, the country was also having to navigate global economic disruptions caused by ongoing wars and geopolitical tensions.
He said the World Bank understood the realities facing Bangladesh and supported the government’s policy approach to overcoming the economic difficulties.
“The World Bank is aligned with the programmes and policy direction we have set to restore economic stability and ensure future development,” the minister said, adding that both sides would continue working together.
He said the World Bank was willing and prepared to provide the assistance Bangladesh needed.
No decision yet on proposed $10 billion in additional assistance
Clarifying reports that Bangladesh had sought an additional $10 billion in assistance from the World Bank, the finance minister said no final decision had been made.
He said discussions with the lender were ongoing and that possible proposals would be reviewed in light of those discussions. The process could take several months to complete, he added.
“No decision is being made at this stage. I have seen several inaccurate reports here and there. This is a discussion, and there will be follow-up based on these talks. It is a process that will continue over the next few months,” he said.
The minister stressed that the ongoing discussions should not be interpreted as a final agreement. Rather, they were intended to establish a basis for determining the next steps and considering possible decisions.
Further discussions would also take place in Dhaka, he said.
Expressing satisfaction with the progress of the talks, Amir Khasru said Bangladesh was in a favourable position to establish a framework for future cooperation.
He reiterated that the government’s economic policies, programmes and medium- and long-term development plans were broadly aligned with the World Bank’s position.
Government’s economic agenda aligned with BNP manifesto
The finance minister also said the World Bank’s position was consistent with the government’s economic plans and the Bangladesh Nationalist Party’s (BNP) election manifesto.
He said discussions were underway on how to address the country’s economic challenges and achieve the government’s development objectives.
According to the minister, the government has submitted a written proposal outlining a framework for partnership with the World Bank. Discussions on the proposed framework will continue.
He said the World Bank had provided various recommendations and suggestions, while Bangladesh had also presented its own proposals and recommendations.
Further discussions would be based on these submissions, he added.
Government optimistic about inflation and GDP targets
Asked about forecasts by the World Bank and the Asian Development Bank (ADB) on inflation and gross domestic product (GDP) growth, and how they compared with the government’s targets, the finance minister said the government did not intend to dispute the projections made by other institutions.
He said the institutions had prepared their forecasts based on their own calculations and analyses, adding that the country’s economic performance would become clearer as progress on key indicators was assessed over time.
“We do not want to dispute anyone’s projections. They have made their estimates based on their own calculations. We are carrying out our work, and they are doing theirs. What matters most is that the cooperation we need continues,” he said.
The minister expressed optimism that the government would be able to meet the inflation targets set out in the national budget.
He said the government was working to restore economic stability through continued engagement with the World Bank, implementation of its economic policies and progress on medium- and long-term development plans.