Economy
Why $12.2b export proceeds pending abroad in 9 months of FY24?

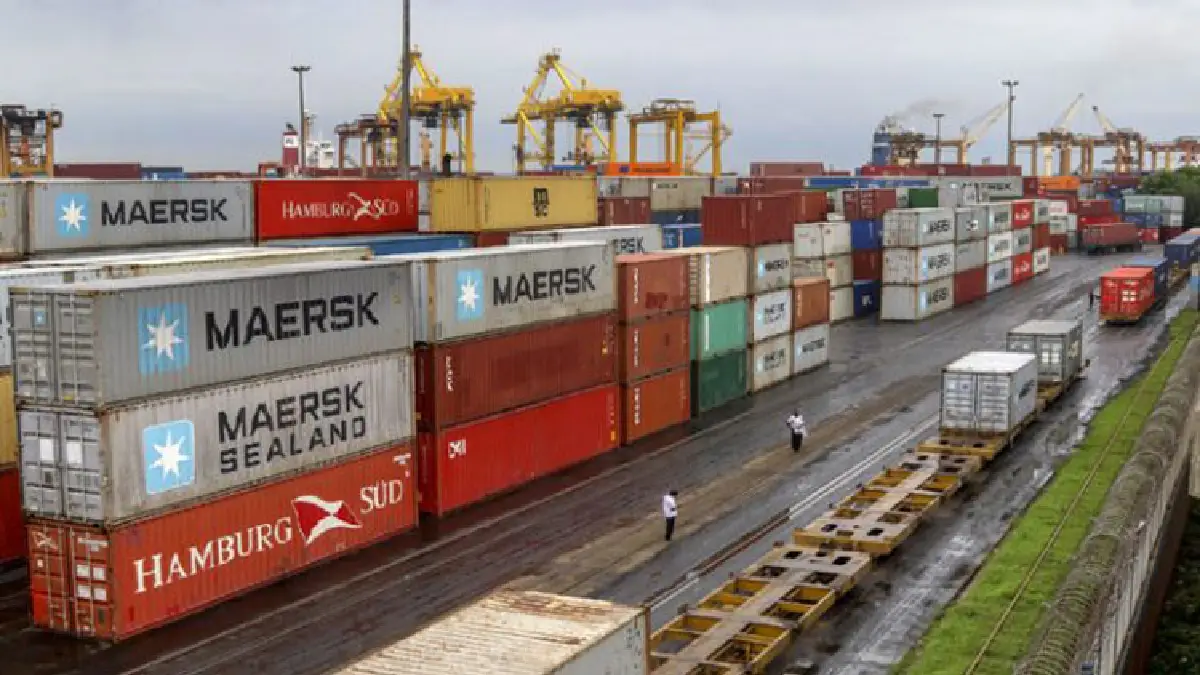
When the country is in dire need of dollars amid a fast erosion of its foreign exchange reserves, $12.2 billion of its total export proceeds remained pending abroad in the first nine months of the fiscal 2023-24 – taking the gap between export receipts and shipment value to a historic high.
Bangladesh Bank data shows that export shipment value, as reported by the Export Promotion Bureau (EPB), was $40.8 billion in July-March of FY24. However, export receipts through the banking channel were $28.6 billion. The gap of $12.2 billion was reflected in trade credit, a component of the financial account of the country’s balance of payment statement.
The widening gap between export realisations and shipment value has put pressure on the country’s financial account, as it is reflected in trade credit. The deficit in the financial account reached a record high of $9.2 billion in July-March, compared to $2.9 billion in the same period of the previous fiscal year, according to central bank data.
Earlier in the FY23, export receipts fell short of the value of shipments by $12 billion, a historic high, raising concerns among the Bangladesh Bank. However, this figure may be even higher by the end of FY24 if the current trend continues.
When contacted, a senior executive of the Bangladesh Bank, involved in preparing the balance of payment statement, explained the rising trade gap, saying that they found a significant mismatch between the EPB-reported export data and the realisation of export proceeds.
The central bank is now working to find out whether export proceeds are not coming home or if there is a problem with the shipment value reported by the EPB, he said.
He added that if any mismatch is identified in accounting between the shipment and realisation values of exports, it will ease the pressure on the financial account.
When asked for an official comment on this matter, Bangladesh Bank Spokesperson Md Mezbaul Haque did not respond.
At present, trade credit reflects the highest negative value among all components of the financial account statement. Trade credit became negative $12.24 billion from July-March of FY24, compared to only $3.96 billion in the corresponding period of the previous year.
Central bank data shows that trade credit has turned significantly negative from positive since last fiscal year, with a widening gap between export shipment and realised value.
In the FY22, trade credit was a positive $311 million, and the financial account had a surplus of $16.6 billion.
Though the unrealised export value is rising, bankers have been experiencing a general trend in export repatriation.
When speaking to the news reporter, a senior executive of a private commercial bank said that the export repatriation trend is normal in his bank. He emphasised, “If exporters do not repatriate their proceeds, how will they run their factories?”
While common factors such as time lag and export bill discounts can account for mismatches between shipment and realised values, a senior executive at the Bangladesh Bank noted that the recent trend of unrealised export proceeds is unusually high.
The mismatch between export shipment and realised value has been notably pronounced over the last two years since FY22, following Bangladesh Bank’s decision to devalue the taka amidst a rising dollar crisis.
In the FY22, unrealised export proceeds reached $8.4 billion, with export receipts lagging 16% behind the shipment value of $52 billion, as disclosed by Bangladesh Bank data in the publication titled “Export Receipts of Goods and Services.”
Central bank data demonstrated that unrealised export proceeds ranged from 10% to 12% of the export shipment value between FY07 and FY21, with figures varying from $1 billion to $5 billion.
Responding to queries regarding the escalating value of unrealised exports during a monetary policy announcement event in June last year, Bangladesh Bank Governor Abdur Rouf Talukder explained that some exporters were deliberately delaying the repatriation of export proceeds to capitalise on currency devaluation.
He mentioned that exporters were permitted to retain export proceeds in their Export Retention Quota (ERQ) account, with a six-month time lag existing between shipment and receipt.
However, he expressed optimism that the Bangladesh Bank’s issuance of a circular to deter gains from devaluation would contribute to reducing the unrealised export value.
Earlier in March last year, the central bank issued a circular stating that exporters would be paid based on the dollar rate on the 120th day of export shipment, even if the proceeds came later. However, this circular seems to have had no impact on export repatriation.
Later, in another circular issued on 20 May, the Bangladesh Bank revised that policy, allowing exporters to receive the dollar rate on the day of encashing export proceeds. As a result, exporters will have an opportunity to receive the current dollar rate even if they encash the export proceeds after the 120th day.

The International Monetary Fund (IMF) has urged Bangladesh to maintain a tight monetary policy to contain inflation, while stressing that monetary tightening alone will not be enough to restore economic stability.
Inflation in Bangladesh rose to 8 per cent in September, according to the IMF. The Washington-based lender has called for broader reforms in the financial sector, stronger revenue mobilisation and improvements in overall economic management to address the country’s persistent economic challenges.
Sonali Jain-Chandra, deputy director of the IMF’s Asia and Pacific Department, made the remarks in response to a question at a news conference on the economic outlook for Asia and the Pacific, held on the sidelines of the IMF and World Bank Group annual meetings in Bangkok, Thailand.
Asked whether tight monetary policy alone would be sufficient to tackle inflationary pressures that have persisted for more than three and a half years, Jain-Chandra said maintaining a restrictive monetary stance was important, but needed to be accompanied by other reforms.
Bangladesh is currently facing challenges in three key areas: revenue mobilisation, the financial sector and inflation, she said.
The IMF also expressed concern over the fragile state of Bangladesh’s financial sector, saying a credible reform strategy was needed to strengthen the sector’s capacity and ensure stability.
The fund also highlighted the country’s persistently weak revenue collection. Bangladesh’s tax-to-GDP ratio has declined over time and currently stands at around 7 per cent, placing it among the lowest in the world, according to the IMF.
The IMF stressed the need for a coordinated effort to increase revenue collection, saying higher government revenues were essential to finance development expenditure and strengthen the financial sector.
It called for necessary reforms to the revenue system and effective measures to improve the government’s capacity to generate income.
Talks Under Way on New IMF Programme
Meanwhile, discussions are continuing on a potential new lending programme for Bangladesh.
Jain-Chandra said Bangladeshi authorities approached the IMF in May for support under a new programme after deciding not to draw further instalments under the previous arrangement.
In response to the request, an IMF mission visited Dhaka in July to discuss various aspects of Bangladesh’s economic reform agenda.
According to Jain-Chandra, the reform issues discussed during the visit were closely aligned with the recommendations outlined in the IMF’s Article IV consultation for Bangladesh earlier this year.
The IMF has remained in regular contact with Bangladeshi authorities since the July visit, she said.
Jain-Chandra added that the fund remained closely engaged with the authorities and was ready to support Bangladesh in initiating the reforms needed to address its economic challenges.
The International Monetary Fund (IMF) has projected that Bangladesh’s gross domestic product (GDP) will grow by 3.2 per cent in the 2026-27 fiscal year, while average inflation could rise to 10.9 per cent, signalling mounting pressure on the country’s economy.
The projections were outlined in the IMF’s World Economic Outlook (WEO) report, released on Tuesday.
The latest growth forecast marks a significant downward revision from the 4.3 per cent projected by the IMF in April. The fund had subsequently forecast growth of 3.5 per cent in July before lowering its estimate further to 3.2 per cent.
The IMF has also sharply revised its inflation outlook for Bangladesh. In April, it projected average inflation of 6 per cent for the 2026-27 fiscal year. The latest estimate raises that figure to 10.9 per cent.
The combination of slower economic growth and persistently high inflation points to continued pressure on Bangladesh’s macroeconomic stability.
Bangladesh growth outlook trails other forecasts
The IMF’s latest growth projection for Bangladesh is lower than those of other major international development institutions.
The World Bank has forecast GDP growth of 3.4 per cent for Bangladesh in the 2026-27 fiscal year, while the Asian Development Bank (ADB) has projected growth of 4 per cent.
According to the IMF, Bangladesh’s economy grew by 3.6 per cent in the 2025-26 fiscal year, following growth of 3.5 per cent in the preceding fiscal year.
India, Bhutan expected to grow faster
The IMF has projected stronger economic growth in neighbouring countries, with India’s economy expected to expand by 7 per cent and Bhutan’s by 6.9 per cent in the relevant fiscal year.
The contrasting forecasts highlight the challenges facing Bangladesh as it seeks to restore economic momentum while tackling persistent inflation.
The IMF’s latest projections come as the annual meetings of the IMF and the World Bank Group are underway in Bangkok, Thailand.
Bangladesh’s economic situation, reform programmes and efforts to secure financing from development partners are among the key issues receiving attention during the meetings.
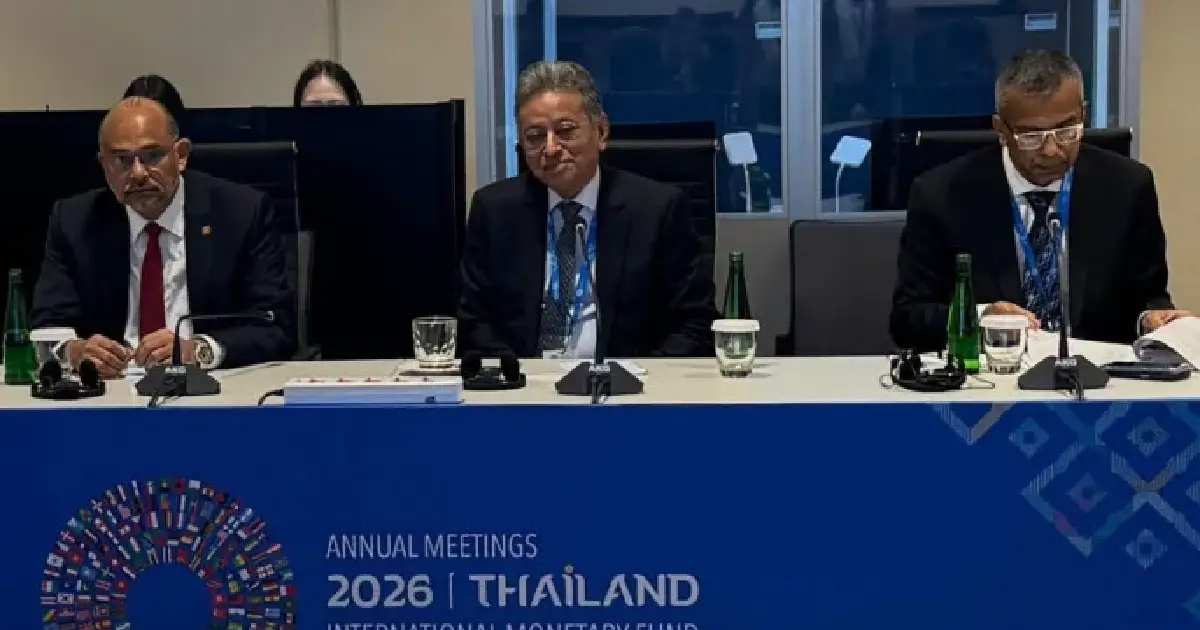
The World Bank supports the Bangladesh government’s policies to address the country’s current economic challenges, restore stability and implement medium- and long-term development plans, Finance Minister Amir Khasru Mahmud Chowdhury said on Tuesday.
He said the global lender was broadly aligned with Bangladesh’s economic programmes and policy priorities and would continue to support the country’s economic recovery and future development.
The finance minister made the remarks while speaking to journalists after a meeting with a World Bank managing director in Bangkok, Thailand, on October 13.
Amir Khasru said Bangladesh’s economy was facing significant challenges when the current government took office. Alongside dealing with the financial and economic burdens inherited from the previous period, the country was also having to navigate global economic disruptions caused by ongoing wars and geopolitical tensions.
He said the World Bank understood the realities facing Bangladesh and supported the government’s policy approach to overcoming the economic difficulties.
“The World Bank is aligned with the programmes and policy direction we have set to restore economic stability and ensure future development,” the minister said, adding that both sides would continue working together.
He said the World Bank was willing and prepared to provide the assistance Bangladesh needed.
No decision yet on proposed $10 billion in additional assistance
Clarifying reports that Bangladesh had sought an additional $10 billion in assistance from the World Bank, the finance minister said no final decision had been made.
He said discussions with the lender were ongoing and that possible proposals would be reviewed in light of those discussions. The process could take several months to complete, he added.
“No decision is being made at this stage. I have seen several inaccurate reports here and there. This is a discussion, and there will be follow-up based on these talks. It is a process that will continue over the next few months,” he said.
The minister stressed that the ongoing discussions should not be interpreted as a final agreement. Rather, they were intended to establish a basis for determining the next steps and considering possible decisions.
Further discussions would also take place in Dhaka, he said.
Expressing satisfaction with the progress of the talks, Amir Khasru said Bangladesh was in a favourable position to establish a framework for future cooperation.
He reiterated that the government’s economic policies, programmes and medium- and long-term development plans were broadly aligned with the World Bank’s position.
Government’s economic agenda aligned with BNP manifesto
The finance minister also said the World Bank’s position was consistent with the government’s economic plans and the Bangladesh Nationalist Party’s (BNP) election manifesto.
He said discussions were underway on how to address the country’s economic challenges and achieve the government’s development objectives.
According to the minister, the government has submitted a written proposal outlining a framework for partnership with the World Bank. Discussions on the proposed framework will continue.
He said the World Bank had provided various recommendations and suggestions, while Bangladesh had also presented its own proposals and recommendations.
Further discussions would be based on these submissions, he added.
Government optimistic about inflation and GDP targets
Asked about forecasts by the World Bank and the Asian Development Bank (ADB) on inflation and gross domestic product (GDP) growth, and how they compared with the government’s targets, the finance minister said the government did not intend to dispute the projections made by other institutions.
He said the institutions had prepared their forecasts based on their own calculations and analyses, adding that the country’s economic performance would become clearer as progress on key indicators was assessed over time.
“We do not want to dispute anyone’s projections. They have made their estimates based on their own calculations. We are carrying out our work, and they are doing theirs. What matters most is that the cooperation we need continues,” he said.
The minister expressed optimism that the government would be able to meet the inflation targets set out in the national budget.
He said the government was working to restore economic stability through continued engagement with the World Bank, implementation of its economic policies and progress on medium- and long-term development plans.